Key economic indicators of Ukraine and the world for May 2025
The article presents the key macroeconomic indicators of Ukraine and the global economy as of the end of April 2025. The analysis is based on current data from the State Statistics Service of Ukraine (SSSU), the National Bank of Ukraine (NBU), the International Monetary Fund (IMF), the World Bank, and leading national statistical offices (Eurostat, BEA, NBS, ONS, TurkStat, IBGE). The Director for Marketing and Development of Interfax-Ukraine, Maksym
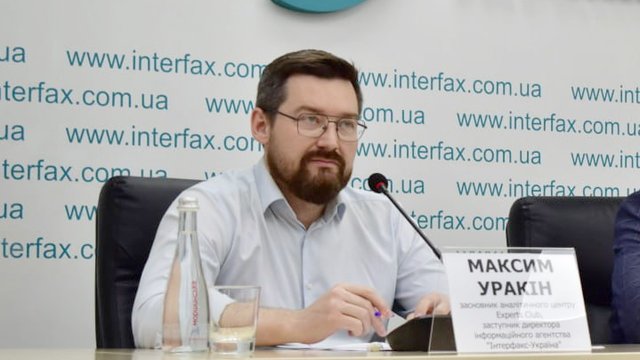
The article presents the key macroeconomic indicators of Ukraine and the global economy as of the end of April 2025. The analysis is based on current data from the State Statistics Service of Ukraine (SSSU), the National Bank of Ukraine (NBU),
the International Monetary Fund (IMF), the World Bank, and leading national statistical offices (Eurostat, BEA, NBS, ONS, TurkStat, IBGE). The Director for Marketing and Development of Interfax-Ukraine, Maksym Urakin, Candidate of Economic Sciences and founder of the information and analytical center “Experts Club,” presented an overview of current macroeconomic trends.
Macroeconomic indicators of Ukraine
The first four months of 2025 were marked for Ukraine by weak but still positive economic movement. According to the NBU's estimate, real GDP added about +0.5% year on year, and the preliminary calculations of the State Statistics Service subsequently refined the dynamics to about +0.9% y/y and approximately +0.7% q/q. In the context of the full-scale war, the constant threat to infrastructure and logistics, the shortage of long-term capital and limited investment programs, this means above all preserving the functionality of the economic system.
“Half a percent or even one percent of growth is not about afterburners, it is about endurance. We see a revival of domestic demand in trade, logistics and certain high-tech niches. But this is, in essence, a recovery ‘in place’: without a massive investment impulse, without expanding exports with added value, without accessible long-term resources, banks and businesses will not be able to scale. A transition is needed from survival to development – through investment, industrial projects and an export ecosystem,” stresses Maksym Urakin.
Inflationary pressure is slowly easing. Annual inflation in April was estimated at about 13.1% y/y after 14.6% in March; the National Bank held the key rate at 15.5%, combining the targeting of inflation expectations with the stabilization of the foreign exchange market.
“Monetary policy in the 2025 model is about balance. If you tighten too much, we will choke business activity and lending; if you loosen, we will get a new wave of inflation and pressure on the exchange rate. The NBU's task is not simply to ‘hold’ the rate, but to synchronize with fiscal policy, IMF programs and the pace of external inflows, so that every hryvnia of reserves works for recovery rather than for plugging operational holes,” the expert notes.
Foreign trade remains the weak link. In January–April 2025, goods exports were estimated at about $13.31 billion, imports at about $24.82 billion, and the negative balance at approximately $11.51 billion. Structurally, imports consist of energy resources, equipment, transport and chemicals; exports, in turn, continue to depend on raw materials and semi-finished products.
“This is not a situational but a structural deficit: as long as we import energy-intensive goods and technological components and export raw materials, the risk to the balance of payments will not disappear. The way out lies in creating production chains inside the country, localizing components, advancing the development of logistics and port infrastructure, insuring war risks and insuring export credits. We need a policy of export-oriented industrial transformation, not just ‘VAT refunds,’” stresses Maksym Urakin.
A positive buffer remains the international reserves, which reached a historic high of about $46.7 billion as of May 1, 2025. The growth was driven by inflows from partners and a decline in the NBU's net interventions.
“Reserves of over 40 billion are an air cushion, but they are not the wealth of the country. A reserve is a credit of trust that must be converted into industrial modernization. If we dissolve this resource in consumption and imports, it will run out, and the structural problems will remain. If instead we direct it to financing exports, insuring investments, infrastructure and technology, we will get a multiplier and productivity growth,” stresses the economist.
The debt burden also remains high: the total government and guaranteed debt as of April 30, 2025 was estimated at about UAH 7.48 trillion (the equivalent of almost $180 billion). This supports budget sustainability “here and now,” but makes coordination with international programs, restructuring of obligations and the launch of projects that generate foreign-currency revenue critically important.
“Debt is not an enemy when it works for development. Our maturity test is to convert the debt resource into production investment rather than consumption. We need transparent project pipelines: from the preparation of feasibility studies to long-term money under government guarantees, from export insurance to industrial parks and clusters. Only in this way will we break the inertia of import dependence,” sums up the founder of “Experts Club.”
The global economy
At the start of the second quarter of 2025, the world is moving in a mode of moderate growth with heightened uncertainty. In its April WEO, the IMF estimated global GDP growth in 2025 at about 2.8%, with slowly fading inflation but an uneven geography of demand. In the US, real GDP in the first quarter, by the annualized methodology, fell by about 0.3% q/q because of “re-importing” and weaker government spending, while core PCE inflation in April remained at about 2.2% y/y, which allows the Fed to maintain a restrained stance.
China held on to about +5.3% y/y in the first quarter, but weakness in real estate and consumer caution limit the horizon for acceleration.
The eurozone, according to preliminary estimates at the end of April, added about +0.4% q/q (+1.2% y/y), and the EU about +0.3% q/q, registering the first signs of an exit from long stagnation. The UK was a positive exception among the G7 with approximately +0.7% q/q in the first quarter. Turkey reported strong growth of about +7.4% y/y against the background of extremely high inflation of about 70% y/y in April, which forces the central bank to maintain a tight course. India retains leadership among the large economies with about +7.4% y/y at the beginning of the year and moderate CPI inflation of about 3.3% in April.
Brazil showed about +0.8% q/q (+2.6% y/y) in the first quarter, but IPCA inflation rose to approximately 5.5% y/y, which restrains the room for a rapid easing of policy.
“The global picture is a mosaic of different speeds and different risks. The US technically has a weak quarter, but domestic demand is still holding; Europe is showing a gradual revival without a breakthrough; China is meeting its growth plan but needs a new model of domestic demand; India is the flagship of dynamism and innovation; Turkey has paid for the impulse with inflation; Latin America is balancing between regulation and stimulus. What matters to Ukraine is not only the partners' figures but their policies: where they are buying more steel and food, where they are building logistics and energy, where windows are opening for suppliers of engineering products. Our task is to guess not past but future demand, and to take the niche before someone else takes it. This means: insurance of export risks, fast customs corridors, long-term money for modernization, specialization of clusters and – what is key – discipline of execution. Without this we will remain a country of imports and of large reserves that are melting away; with it we can become a country of exports and of large projects that work,” sums up Maksym Urakin.
Key takeaways
In sum, as the second quarter begins, Ukraine's economy is in a phase of sustained balance: modest growth, slowing inflation and record reserves are set against a deep trade gap and a heavy debt burden. The solution lies in accelerating structural change: investment in industry and logistics, high value-added exports, coordination with international programs, and turning the debt resource into a driver of productivity. As Maksym Urakin stresses, “the window of opportunity for transformation is already open – the only question is whether we can pass through it fast enough.”
A more detailed analysis of Ukraine's economic indicators is available in the monthly information and analytical products “Economic Monitoring” of the Interfax-Ukraine agency.
Head of the “Economic Monitoring” project, candidate of economic sciences Maksym Urakin