Key Economic Indicators of Ukraine and the World in 2026
The article presents key macroeconomic indicators of Ukraine and the global economy as of the end of February 2026. The analysis is based on current data from the State Statistics Service of Ukraine (SSSU), the National Bank of Ukraine (NBU), the International Monetary Fund (IMF), the World Bank, as well as leading national statistical agencies (Eurostat, BEA, NBS, ONS, TurkStat, IBGE). Maksym Urakin, Candidate of Economic Sciences and founder…
The article presents key macroeconomic indicators of Ukraine and the global economy as of the end of February 2026. The analysis is based on current data from the State Statistics Service of Ukraine (SSSU), the National Bank of Ukraine (NBU), the International Monetary Fund (IMF), the World Bank, as well as leading national statistical agencies (Eurostat, BEA, NBS, ONS, TurkStat, IBGE). Maksym Urakin, Candidate of Economic Sciences and founder of the Experts Club information and analytical center, presented an overview of the current macroeconomic trends that shaped the situation in Ukraine and the world at the beginning of 2026.
Macroeconomic indicators of Ukraine
As of the end of February 2026, the Ukrainian economy maintained a regime of managed macro-financial stabilization, but compared with January the balance of risks became less comfortable. After the NBU began a cycle of cautious monetary easing, inflation accelerated slightly again, international reserves declined from historically high levels, and the foreign exchange market required significant interventions by the regulator. At the same time, the overall macro-financial situation remained under control thanks to the high level of reserves, external support, continued demand for hryvnia instruments and the adaptability of businesses.
The Ukrainian economy ended 2025 with positive but moderate dynamics. According to National Bank of Ukraine estimates, real GDP grew by 1.8% in 2025. This meant the recovery trend was maintained, but the pace of growth was far below the needs of post-war reconstruction. The main constraints remained the consequences of the war, labor shortages, damage to energy infrastructure, weak external demand for part of Ukrainian exports and a high level of uncertainty for investment.
For 2026, the NBU also forecast economic growth of 1.8%. This estimate reflected a cautious scenario: domestic demand and budget spending supported economic activity, but energy risks, wartime losses and limited export opportunities gave no grounds to speak of a rapid acceleration.
“February 2026 showed that Ukraine is so far not in a phase of full-fledged recovery, but in a phase of maintaining macroeconomic manageability. The positive indicators rely to a large extent on external financing, budget demand, NBU policy and business adaptation. This creates a stabilizing effect, but does not yet form a sufficient internal basis for long-term growth. To move to a new quality of recovery, Ukraine needs not only reserves and partner assistance, but also a build-up of production, exports, energy autonomy and investment in human capital,” Urakin noted.
The inflation picture in February became one of the main signals for macroeconomic policy. According to State Statistics Service data commented on by the NBU, consumer inflation in February 2026 accelerated to 7.6% year on year, while prices rose by 1.0% month on month. Core inflation remained at 7.0% year on year. This meant that after the slowdown in January, inflationary pressure had not disappeared completely, and some of its components began to strengthen again.
The NBU explained the February dynamics by, among other things, the rising prices of raw foodstuffs, the growing cost of certain services, the impact of the energy situation on business costs and some acceleration in fuel prices. At the same time, the regulator noted that the overall inflation trajectory remained close to the forecast. This made it possible not to revise the monetary strategy abruptly, but forced it to remain cautious on the question of further rate cuts.
At the end of February, the NBU key policy rate stood at 15.0%. After the cut at the end of January, the regulator effectively took a pause, assessing how sustainable the disinflation trend was. This approach looked logical: the real yield on hryvnia instruments remained an important factor restraining demand for foreign currency, and the foreign exchange market continued to require the active participation of the National Bank.
“The February acceleration in inflation was not critical, but it clearly showed the limits of rapid monetary easing. Ukraine cannot afford a sharp cheapening of money merely for the sake of short-term economic stimulus, since this could boost demand for foreign currency and destabilize inflation expectations. In current conditions, the NBU has to balance between supporting economic activity and preserving confidence in the hryvnia. That is why every further step in cutting the rate must be very cautious and tied to a real easing of risks,” Urakin stressed.
The foreign exchange sector remained under control but tense in February. As of March 1, 2026, Ukraine’s international reserves stood at about $54.8 billion. That was 5% less than at the start of February, but the level of reserves remained historically high and corresponded to roughly 5.7 months of future imports. The decline in reserves was driven mainly by NBU interventions in the foreign exchange market and by the state’s debt payments in foreign currency.
In February, the National Bank’s net sale of foreign currency amounted to almost $3 billion. This indicated the persistence of a structural foreign currency deficit in the private sector. Inflows of external financing partly offset this pressure but did not eliminate the problem itself: the Ukrainian economy imports far more goods than it exports, so currency stability will continue to depend significantly on international assistance and NBU reserves.
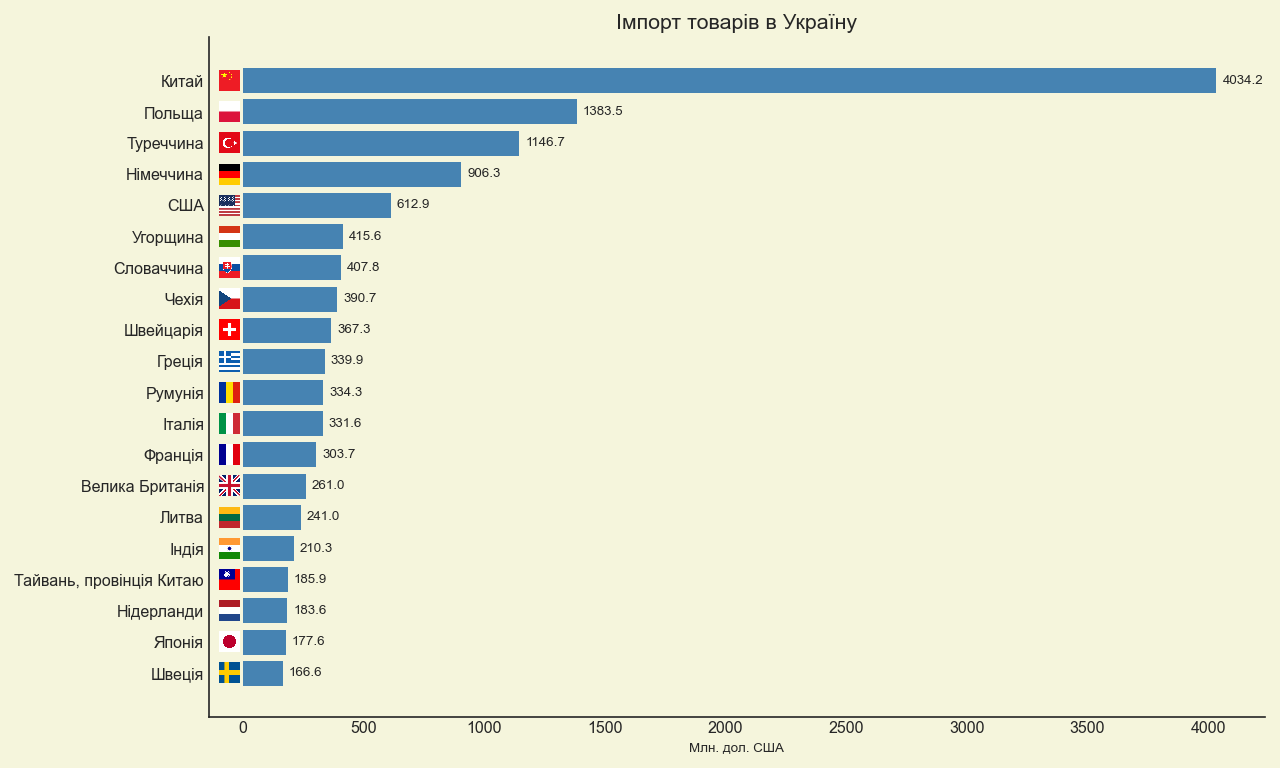
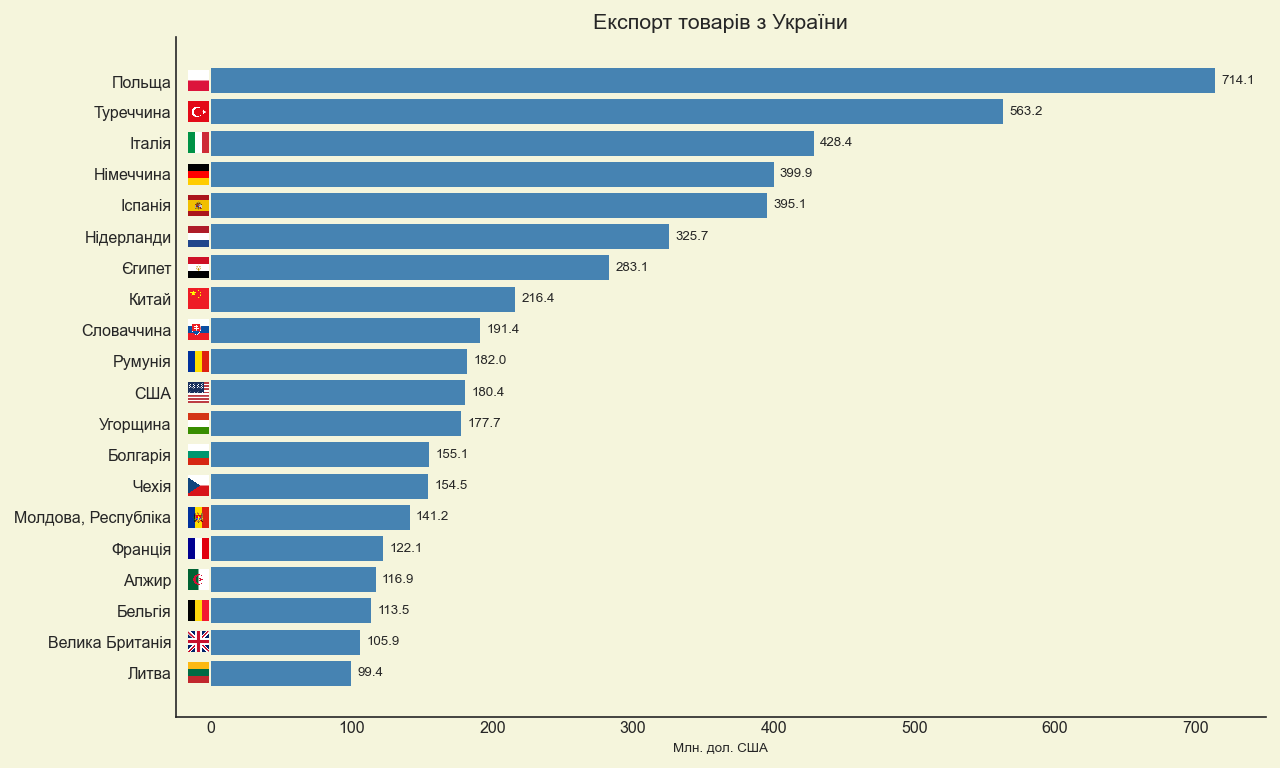
Foreign trade remained one of the weakest elements of the macroeconomic structure. According to the State Customs Service, Ukraine’s trade turnover in January–February 2026 amounted to $21.3 billion. Imports reached $14.8 billion, while exports were only $6.5 billion. As a result, the goods trade deficit over the two months exceeded $8 billion. This meant that imports were more than double exports, and domestic demand for foreign goods, energy resources, equipment and consumer goods remained far higher than the foreign currency earnings from selling Ukrainian products abroad.
The largest sources of imports remained China, Poland and Türkiye. Machinery, equipment, vehicles and fuel and energy goods played an important role in the import structure. The largest destinations for Ukrainian exports were Poland, Türkiye and Italy, while the basis of exports remained foodstuffs, metals and certain mechanical engineering items. This structure confirms that Ukraine does not yet have a sufficiently diversified export base to reduce the trade deficit quickly.
“It is foreign trade that is the key indicator of long-term resilience. Record reserves and international aid can stabilize the situation, but they do not replace the economy’s own export capacity. When imports are more than double exports, it means that the country is financing a significant part of consumption, investment needs and the war economy from external sources. Such a model is justified in wartime, but strategically it cannot be permanent. If Ukraine wants to move from a survival model to a development model, it needs to increase the share of products with higher added value and develop processing, logistics, energy resilience, the defense industrial complex and high-tech production,” Urakin stressed.
The budget situation in the first two months of the year also remained tense. According to the Ministry of Finance, in January–February 2026 revenues of the general fund of the state budget amounted to about UAH 466.8 billion, while cash expenditures of the general fund were about UAH 546.5 billion. Tax revenues, customs payments and international grants played a significant role in revenues, with the latter amounting to more than UAH 160 billion over the two months.
This confirms that Ukraine’s public finances remain functional but structurally dependent on external support. Spending on defense, security, social payments and servicing state obligations creates a very high level of budgetary burden. In such conditions, the regularity of international financing, the government’s ability to raise funds on the domestic market and the preservation of confidence in hryvnia instruments remain critically important.
“Ukraine’s budget in 2026 remains a budget of wartime resilience. Its task is not only to finance defense and social obligations, but also to maintain confidence in public finances. But when a significant part of revenues is directly or indirectly linked to international support, the country cannot afford to lose the regularity of financing. The government must work simultaneously on three tasks: securing external inflows, developing the domestic borrowing market and gradually expanding its own tax base through the recovery of economic activity,” Urakin noted.
Global economy
The global economy as of the end of February 2026 looked more resilient than might have been expected amid high geopolitical tension, debt risks and the restructuring of global supply chains. In its January update of the World Economic Outlook, the International Monetary Fund forecast global economic growth of 3.3% in 2026 and 3.2% in 2027. This meant there was no scenario of a global recession, but it also did not indicate a return to rapid and synchronized growth.
The US remained one of the main stabilizers of the global economy. US real GDP grew by 1.4% at an annual rate in the fourth quarter of 2025 after a much stronger third quarter, and the economy expanded by 2.2% over the whole of 2025. The main drivers were consumer spending and private investment. At the same time, inflation was gradually declining: in January 2026, CPI stood at 2.4% year on year, down from 2.7% in December 2025. At the end of January, the Federal Reserve kept the federal funds rate range at 3.5–3.75%.
In Ukraine's case, the dynamics of the American economy had a dual significance. On the one hand, the resilience of the US supported global demand and financial markets. On the other, the persistence of relatively high interest rates meant that global liquidity remained not particularly cheap, and countries with elevated risk found it harder to count on a sharp fall in the cost of capital.
The eurozone was in a different phase of the cycle. Its economy showed weaker growth, but inflation was closer to target. According to Eurostat estimates, eurozone GDP grew by 0.3% quarter on quarter in the fourth quarter of 2025 and by about 1.5% over the whole of 2025. At the start of 2026, the European Central Bank kept the deposit facility rate at 2.0%, the main refinancing operations rate at 2.15%, and the marginal lending facility rate at 2.40%. The inflation backdrop in the eurozone in February remained close to the target level.
In Ukraine's case, the European economy is the key external environment, through trade, financing, migration, logistics and the process of integration into the EU. However, weak eurozone growth means that external demand from European partners is unlikely to become a powerful stand-alone driver of Ukrainian exports in 2026. Ukraine should focus not only on volumes of raw-material supplies but also on production integration into European value chains.
The United Kingdom remained an example of an economy with moderate growth and a still elevated inflation backdrop. After weak momentum at the end of 2025, the British economy entered 2026 cautiously: the services sector remained the main support, while industry and construction did not provide a strong impetus. Inflation in January 2026 slowed to 3.0% year on year but still exceeded the Bank of England's target. This limited the room for rapid monetary easing.
“The global economy at the beginning of 2026 did not look crisis-ridden, but it cannot be called uniformly strong. The US maintained positive momentum, although no longer at an overheated pace; the eurozone was effectively balancing between low inflation and weak growth; the UK had slow growth but a still elevated inflation backdrop. In Ukraine's case, this means that external demand is unlikely to become a powerful stand-alone driver of recovery. The global environment rather creates moderately favorable financial conditions but does not guarantee automatic growth of Ukrainian exports,” Urakin noted.
China ended 2025 with a formally strong result: the country's GDP grew by 5.0%, to more than 140 trillion yuan. In February 2026, consumer inflation in China was 1.3% year on year, which was higher than the previous weak readings but still pointed to moderate domestic price pressure. China retained a powerful manufacturing and export base, but domestic demand, the property market and the debt burden remained important constraints.
India, by contrast, remained one of the most dynamic large markets in the world. According to the government's first advance estimate, India's real GDP in the 2025/26 fiscal year was expected to grow by 7.4%, and the growth rate in the third quarter of the fiscal year was estimated at 7.8%. The main driver remained the services sector, along with domestic demand. Inflation in India at the beginning of 2026 remained moderate, which created favorable conditions for maintaining strong economic momentum.
Turkey at the start of 2026 continued to show a combination of economic growth and high inflation. According to official estimates, Turkey's GDP grew by 3.6% in 2025, but inflation in February 2026 exceeded 31% year on year. This meant that the country maintained business activity and domestic demand, but at the price of high price pressure and the need for tight macroeconomic policy.
Brazil looked more balanced. Its GDP in 2025 grew by 2.3%, to 12.7 trillion reais in current prices, and IPCA inflation for 2025 as a whole was 4.26%. Growth was supported by the agricultural sector, services and industry. For the global economy, Brazil remained an important example of a large market combining commodity potential, domestic demand and a relatively controlled inflation backdrop.
“China, India, Turkey and Brazil show very well how different the dynamics of large emerging economies have become. China has great scale and a strong manufacturing base, but still faces structural imbalances and insufficiently strong domestic demand. India demonstrates the most convincing combination of high growth and moderate inflation. Turkey maintains momentum, but the price of this growth is a very high inflation backdrop. Brazil is moving more moderately, but in a more balanced way. In Ukraine's case, it is important to look at these examples in practical terms: in global competition, the winners are those economies that are able to sustain macroeconomic stability, a production base, exports and domestic investment demand at the same time,” Urakin believes.
Conclusions
As of the end of February 2026, Ukraine retained macro-financial manageability, but February showed that stabilization remains fragile. Inflation accelerated to 7.6% y/y, the policy rate remained at 15.0%, international reserves fell to about $54.8 billion, and the foreign exchange market required almost $3 billion of net NBU interventions over the month. At the same time, reserves remained sufficient, the budget was executed with the support of domestic revenues and international grants, and the economy maintained positive momentum.
The main weak points of the Ukrainian economy remained the large trade deficit, the budget's dependence on external financing, war risks, the labor shortage, energy vulnerability and insufficient export diversification. Positive factors were high international reserves, controlled monetary policy, business adaptability, continued international support and the preserved functionality of public finances.
The global economy at the same moment demonstrated moderate resilience. The IMF forecast global growth of 3.3% in 2026. The US remained strong, but without excessive overheating; the eurozone balanced between weak growth and near-target inflation; China retained its scale but had structural challenges; India remained the main growth driver among large economies; Turkey struggled with high inflation; Brazil showed moderately positive momentum.
“February 2026 was a reminder for Ukraine that macro-financial stability in wartime conditions is not a final result but a process of constant balancing. The country has a financial cushion in the form of reserves and partner support, but long-term resilience will depend on the ability to create its own economic base for growth. For this, investments in energy, processing, logistics, export production, technology and human capital remain critically important in 2026. Without this, even high reserves and external assistance will remain only a financial cushion rather than a source of long-term development,” Urakin concluded.
The monthly analytical and statistical product “Economic Monitoring” is available to clients of Interfax-Ukraine.
Head of the “Economic Monitoring” project, Director of Development and Marketing at Interfax-Ukraine, Maksym Urakin