Key economic indicators of Ukraine and the world in the first quarter of 2025
The article presents the key macroeconomic indicators of Ukraine and the global economy as of April 1, 2025. The analysis is based on current data from the State Statistics Service of Ukraine, the National Bank of Ukraine, the International Monetary Fund, the World Bank and the UN. Maksym Urakin, Director of Marketing and Development at “Interfax-Ukraine”, candidate of economic sciences and founder of the information and analytical center “Experts Club”, presented an overview of current macroeconomic
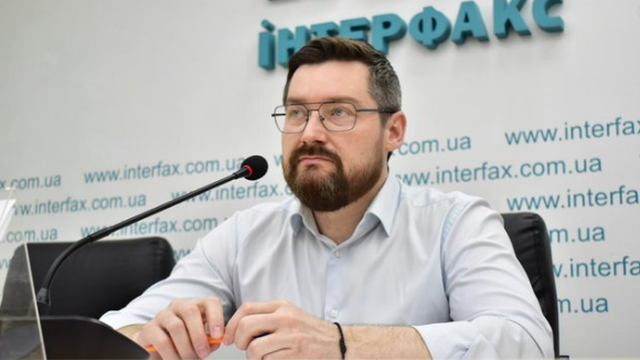
The article presents the key macroeconomic indicators of Ukraine and the global economy as of April 1, 2025. The analysis is based on current data from the State Statistics Service of Ukraine, the National Bank of Ukraine, the International Monetary Fund, the World Bank and the UN. Maksym Urakin, Director of Marketing and Development at “Interfax-Ukraine”, candidate of economic sciences and founder of the information and analytical center “Experts Club”, presented an overview of current macroeconomic trends.
Macroeconomic indicators of Ukraine
The first quarter of 2025 was a period of slow but still positive economic movement for Ukraine. According to updated estimates by the National Bank of Ukraine, the country's real GDP grew by 0.5% year on year, indicating gradual stabilization after an unstable start to the year. This growth is not high by international standards, but amid a full-scale war, a constant threat to infrastructure and logistics, and limited access to capital, such a result is seen as a positive signal.
“Half a percent of GDP growth in the first quarter is rather an indicator that the system has remained viable than a measure of development. The domestic market has begun to revive, especially in consumption, logistics and some technology sectors. But for now this is mostly growth ‘in place’ – without an investment impulse, without exports, without a long-term resource base,” explains Maksym Urakin.
One of the main challenges remains inflation. As of March 2025, annual inflation was about 12.6%, which has barely changed compared with February but shows a trend toward gradual slowing. The NBU points to the effect of the seasonal decline in food prices, currency stabilization and a balanced monetary policy as key factors restraining the pace of price growth.
“The main thing is to maintain a balance between fighting inflation and preventing a contraction of economic activity. The National Bank's monetary policy in the first quarter was fairly balanced: on the one hand, keeping the key rate unchanged, on the other, mild intervention support for the hryvnia. But we are still far from leaving the inflation risk zone,” the expert stresses.
The state of foreign trade, by contrast, points to a deepening of structural problems. According to preliminary estimates by the Centre for Economic Strategy, the foreign trade deficit reached $3.6 billion in April, the result of imports ($6.3 billion) substantially exceeding exports ($3.1 billion). In the cumulative total for the first quarter, the analysts say, the trade deficit exceeded the figure for the same period of 2024, despite activity in the agricultural sector and the supply of services.
“The worst part is that this deficit is not situational but structural. Imports of energy, equipment, chemical products and transport remain dominant, while exports are mostly limited to raw materials. This jeopardizes currency stability if international financial support ends,” comments the founder of Experts Club.
Against the backdrop of the widening trade gap, the level of international reserves remains a positive signal. According to the NBU, as of April 2025 reserves stood at about $42 billion, a historic high for Ukraine. This growth was made possible by further tranches of financial assistance from the European Union, the United States and the IMF, as well as by the National Bank's successful foreign exchange operations on the interbank market.
“Reserves of over $40 billion are not just a statistic, they are an ‘air cushion’ for a country that lives in a mode of constant risk. But we should not be lulled by this: it is a resource of trust that must be turned into economic recovery, otherwise we will lose it again, as has happened before,” warns Maksym Urakin.
However, the debt burden remains high. According to the latest estimates, Ukraine's total public and publicly guaranteed debt at the beginning of April 2025 stood at about $147.2 billion, or roughly 94% of GDP, of which more than $100 billion is external borrowing. This underscores the country's dependence on external assistance and international financing, in particular IMF, EU and World Bank programs.
Global economy
Global economic indicators as of the beginning of April 2025 point to slowing growth alongside continued inflationary pressure, especially because of new trade risks and geopolitical instability. According to the IMF, global growth has seen an accelerated decline, to 2.8% in 2025, one of the lowest levels in recent decades. Inflation in most regions is gradually declining, but it remains above target, especially in developing countries.
Macroeconomic uncertainty has intensified amid trade protectionism, rising energy prices and geopolitical challenges, which makes forecasting considerably harder. Central banks that have not yet tightened policy find themselves in a wait-and-see mode, and investors are becoming more cautious. Forecasts by Morgan Stanley and S&P Global point to a further weakening of global GDP to 2.2–2.9% in 2025, which negatively affects investor confidence.
According to the BEA, US GDP contracted by −0.3% at an annualized rate in the first quarter of 2025 — the first decline since 2022. This was mostly caused by a sharp increase in imports (advance purchases ahead of possible tariffs) and a cut in government spending. However, final domestic demand remained relatively resilient (+3%). Inflation in March/April was about 2.3–2.6% (PCE), in line with the regulator's expectations; the Fed is holding the rate at 5.25–5.5%, awaiting signs of stabilization.
According to official data, China's GDP grew by +5.4% y/y in the first quarter of 2025, in line with the government's target of around 5%. However, fiscal and monetary constraints, particularly in the real estate sector, are slowing the pace of growth. By May, budget revenues had fallen by 0.3% y/y, indicating weaker economic activity. Stimulus measures are being introduced in response, but their effect is still uncertain.
The European Commission forecasts annual EU GDP growth of +1.1% and +0.9% for the eurozone, with a noticeable improvement in the first quarter (+0.6% q/q), the highest figure since 2022. Inflation in March/April was below 2%, gradually approaching the target level.
According to the ONS, the United Kingdom's GDP grew by +0.7% q/q in the first quarter of 2025, making it the leader among the G7. On an annual basis, growth was about +1%. Inflation in April was around 3.4%, which forces the Bank of England to remain cautious in cutting rates (from 5.25% to 4.5%). However, exceeding the inflation target holds back an acceleration of the economy.
In the first quarter, Turkey showed a positive growth rate — about +2.3% q/q, or ≈ +3.0% y/y. Inflationary pressure remains extremely high — ≈38–39% in March/April, despite the central bank's measures.
The Indian economy continues to show one of the highest growth rates among large countries: in the first quarter of 2025 the rate is +7.4% y/y, while inflation is under control: CPI — ~3.2% in April. The forecast for the 2024–25 fiscal year is +6.3–6.5%.
In the first quarter, Brazil achieved GDP growth of +1.3% q/q (≈+3.5% y/y), the best result in two years. However, inflation rose to 5.48% in April, the highest level since February 2023, and is a source of serious concern.
“At the start of the second quarter, the world shows promise but also high instability. The US has fallen into recession, but domestic demand is still holding. Europe is slowly emerging from crises, and the United Kingdom is showing resilience. China is stable in pace but weak in consumption. India is a model of dynamism and innovation. Turkey is on the verge of an inflation crisis. Brazil is advancing but is at risk because of rising prices. As for Ukraine, it is time to make a decision: will we use the flow of imported resources merely to offset the deficit, or turn it into a chance for a technological and industrial leap?” Maksym Urakin noted.
Conclusion
Ukraine's economy at the start of the second quarter of 2025 is in a phase of sustained equilibrium. Restrained growth, controlled inflation and record reserves are the basic factors of stability. But the deep trade deficit, the debt burden and the lack of investment drivers remain key risks for the medium-term outlook.
The global economic picture remains uneven, with clear geographic imbalances. Ukraine is showing resilience, holding on to growth and record reserves while facing foreign trade challenges. World markets, from the US to India, are shaping new conditions for a strategic solution to these tasks.
A more detailed analysis of Ukraine's economic indicators is available in the monthly information and analytical products of the Interfax-Ukraine agency, “Economic Monitoring”.
Head of the “Economic Monitoring” project, Candidate of Economic Sciences Maksym Urakin